What Is ERISA 404(c)? What 401(k) Plan Sponsors Need to Know
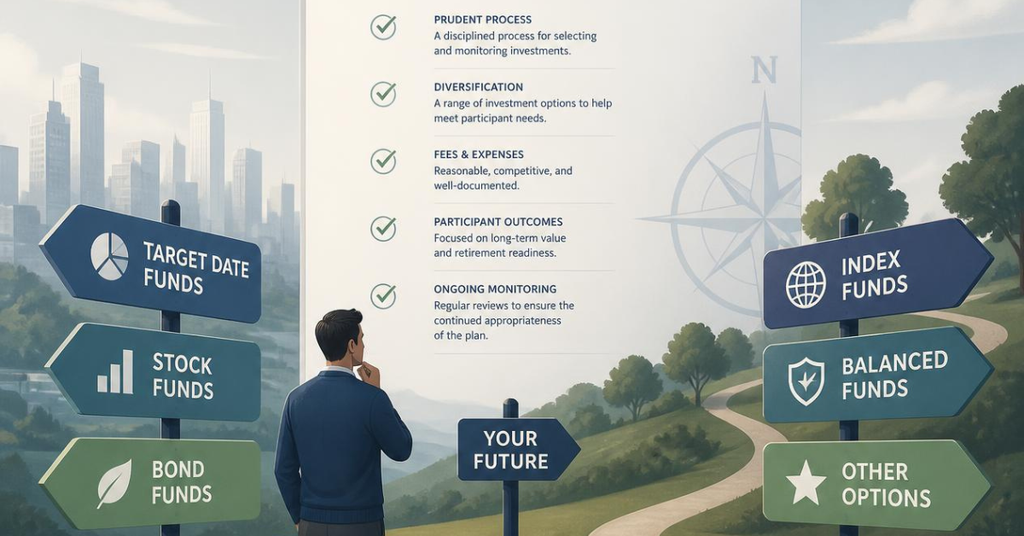
For most 401(k) plans, participants are expected to make their own investment decisions.
They choose between the plan’s investment options and decide how much of their account to put into each option. Next, they may change those elections as their circumstances change.
This raises an important question for plan sponsors:
If a participant chooses an investment and that investment performs poorly, who is responsible?
Now is where ERISA Section 404(c) comes into the conversation.
ERISA 404(c) provides a safe harbor that can limit a plan fiduciary’s liability for losses that are the direct and necessary result of a participant’s exercise of independent control over the assets in their individual account. However, that protection is not automatic. The plan must satisfy the applicable requirements, and the participant must actually exercise independent control.
In other words, 404(c) is useful—but it is not a checkbox.
What Is ERISA 404(c)?
ERISA Section 404(c) applies to certain participant-directed individual account plans, including many 401(k) plans.
The basic concept is straightforward: when participants are given meaningful control over their own retirement account investments and actually exercise that control, certain investment losses resulting directly and necessarily from those choices may fall outside the liability of the plan’s other fiduciaries.
The Department of Labor’s regulation, 29 CFR § 2550.404c-1, establishes the conditions for a plan to qualify as an ERISA 404(c) plan and explains when the liability relief may apply.
A plan does not become a 404(c) plan simply because the recordkeeper offers participants an online investment portal. Likewise, adding a disclaimer to the plan’s enrollment materials does not, by itself, create 404(c) protection.
Instead, the plan has to provide participants with the opportunity to exercise control, a broad range of investment alternatives, the ability to diversify, and sufficient information to make informed investment decisions.
Is ERISA 404(c) Automatic?
No.
This is a really important concepts for plan sponsors and retirement plan committees to understand.
ERISA 404(c) is a safe harbor. To receive the protection, the plan must satisfy the applicable conditions.
The Department of Labor regulation specifically says that the relief applies when a participant or beneficiary has exercised independent control over the investment of assets in their individual account. Whether that independent control exists depends on the facts and circumstances.
So, when a committee says, “Our plan is a 404(c) plan,” the next question should be, “How do we know?”
What Are the ERISA 404(c) Requirements?
The regulation is detailed, but several concepts are particularly important when evaluating whether a participant-directed 401(k) plan is operating as intended under 404(c).
1. Participants must have an opportunity to exercise control
Participants need a reasonable opportunity to give investment instructions to an identified plan fiduciary who is generally obligated to follow those instructions, subject to the limitations in the regulation.
That means participant control needs to be real.
If participants cannot reasonably direct their investments, or if restrictions prevent them from exercising control in the manner contemplated by the regulation, the plan may have a problem satisfying the requirements.
Ask your committee: Can our participants actually control the investments in their accounts?
2. The plan must offer a broad range of investment alternatives
A 404(c) plan must give participants a reasonable opportunity to choose among a broad range of investment alternatives.
The regulation generally requires at least three diversified investment alternatives with materially different risk and return characteristics. Collectively, those alternatives should allow participants to construct portfolios with a range of risk and return characteristics that would normally be appropriate for them.
Notice what this means.
“Three funds” is not necessarily the same thing as a broad range of investment alternatives.
Does the investment menu give participants a reasonable opportunity to make meaningful choices and diversify their accounts?
3. Participants must have an opportunity to diversify
Diversification is another fundamental component.
Participants need a reasonable opportunity to diversify the portion of their account over which they exercise control in order to minimize the risk of large losses, taking into account the nature of the plan and the size of participant accounts.
This is particularly important when a plan offers concentrated investments, employer securities, or other options that could create additional diversification considerations.
A committee should therefore look beyond the existence of an investment menu and ask:
“Does the way our plan operates actually give participants a reasonable opportunity to diversify?”
4. Participants must have sufficient information to make informed decisions
This may be one of the most interesting—and most misunderstood—parts of 404(c).
Participants must be provided, or have the opportunity to obtain, sufficient information to make informed investment decisions concerning the alternatives available under the plan.
That includes the information required under the participant-level disclosure rules, as well as an explanation that the plan intends to qualify as a 404(c) plan and that fiduciaries may be relieved of liability for losses that are the direct and necessary result of participant investment instructions.
And this is where participant education becomes especially important.
ERISA 404(c) and Participant Investment Education
A participant-directed plan can give employees tremendous responsibility over their retirement savings.
But responsibility without information is a pretty shaky arrangement.
The Department of Labor has long provided guidance distinguishing investment education from investment advice. Interpretive Bulletin 96-1 identifies categories of educational information that can generally be provided without becoming investment advice, including general financial and investment concepts, asset allocation models, and interactive investment materials.
That creates an important distinction for plan sponsors.
Education explains. Advice recommends.
For example, explaining diversification, risk and return, inflation, investment time horizons, or how different asset classes generally behave can be investment education. By contrast, telling a particular participant, “You should put 80% of your account into this fund,” moves into individualized advice territory.
The distinction matters because plan sponsors and service providers need to understand what they are actually providing to participants.
And there is another important point: participant education should not be treated as a one-and-done enrollment event.
A single enrollment meeting may help a participant understand the plan. However, participants’ circumstances change. Markets change. Investment options change. Retirement gets closer.
The DOL has recognized the value of investment education that helps participants make informed decisions, while also maintaining the distinction between education and individualized investment advice.
For plan sponsors, that means it is worth asking not simply whether education is offered, but whether participants are receiving useful information in a way that gives them a genuine opportunity to understand their choices.
What ERISA 404(c) Does Not Do
Here’s where some of the confusion starts.
404(c) does not eliminate fiduciary responsibility.
Plan fiduciaries still have responsibilities relating to the plan and its investment options. In particular, the Department of Labor has indicated that fiduciaries retain responsibility for the prudent selection and monitoring of investment options available to participants.
Think about it this way:
The participant gets to choose from the menu.
But the fiduciaries still have to make sure the menu is responsibly designed and maintained.
If a committee selects an investment option for the plan, that selection is a fiduciary decision. Consequently, monitoring that investment is also a fiduciary responsibility.
The fact that participants ultimately choose among the options does not turn off the fiduciary duties that apply to the people responsible for the plan.
What About a QDIA?
Qualified default investment alternatives, or QDIAs, introduce another layer to the conversation.
A QDIA is used when a participant does not provide investment direction and the plan invests the participant’s account in the default investment alternative.
The QDIA regulations provide a separate safe harbor for certain default investments. However, plan fiduciaries remain responsible for the prudent selection and monitoring of the QDIA.
So, once again, the existence of participant direction or a default investment does not mean fiduciary oversight disappears.
Why Should a Plan Sponsor Care About 404(c)?
Plan sponsors must prioritize ERISA Section 404(c) because a participant-directed retirement plan creates a highly complex division of operational responsibilities.
While participants make their own individual investment choices, the plan sponsor and core fiduciaries maintain ultimate oversight. This interconnected ecosystem relies on multiple service providers: investment advisors offer education or advice, recordkeepers manage the trading platform and transaction processing, and third-party administrators (TPAs) handle complex administration and compliance.
When these distinct roles are not clearly understood, administrative overlaps and compliance blind spots can quickly develop into serious operational liabilities. For that reason, establishing a robust fiduciary process requires making every single party’s responsibilities completely visible. You must definitively answer who selects the investment lineup, who monitors performance, who provides participant-level education, who distributes required disclosures, and who follows up to execute corrective actions when something goes wrong.
These vital internal controls become infinitely more powerful—and legally protective—when they are formally documented to establish a clear audit trail.
404(c) Should Be Part of the Annual Fiduciary Review
Integrating a Section 404(c) compliance audit into your committee’s annual fiduciary review is critical for maintaining year-end operational integrity.
The conclusion of the third quarter serves as an ideal operational window to assess whether your plan’s 404(c) process is actually functioning as legally intended. Committees should systematically audit the core components of the plan by evaluating the diversity of the investment menu, reviewing participant-directed trading procedures, and confirming that all mandatory ERISA fee and feature disclosures are being distributed on schedule.
Additionally, you must evaluate the efficacy of participant investment education and re-verify the specific fiduciary boundaries of each service provider. Once the review is complete, you must formally document what was audited, who performed the review, and the committee’s final conclusions.
This final step is vital; establishing a contemporaneous audit trail ensures your compliance history is easily provable to regulatory bodies, rather than forcing the organization to retroactively reconstruct events years down the road during a Department of Labor audit.
The Fiduciary Wise Take
ERISA Section 404(c) functions as a powerful legal safe harbor for participant-directed retirement plans, but securing its protective shield requires strict operational accountability.
To legally shift investment liability away from the organization, the plan must grant participants meaningful independent control, offer a broad, well-diversified lineup of at least three distinct asset classes, and deliver comprehensive, clear disclosure data so employees can make highly informed investment decisions.
Crucially, utilizing this framework does not relieve plan fiduciaries of their permanent duty to prudently select and continuously monitor the designated investment menu. At Fiduciary Wise, we believe effective compliance is an ongoing, active process rather than a passive paragraph buried inside a plan document.
True fiduciary governance demands that you continuously ask critical questions: Are your participants receiving actionable, high-quality investment education? Is your investment menu genuinely diversified to minimize large losses? Are core plan duties unambiguously allocated across the sponsor and your third-party providers?
Most importantly, can your active fiduciary file comprehensively prove this oversight occurred? ERISA provides the regulatory blueprint, but your ongoing fiduciary process is what actually brings compliance to life.
Frequently Asked Questions About ERISA 404(c)
What is ERISA 404(c) in simple terms?
ERISA 404(c) is a safe harbor for certain participant-directed individual account plans. When its requirements are satisfied and a participant independently exercises control over their account, plan fiduciaries may receive relief from liability for losses that are the direct and necessary result of that participant’s investment decision.
Does every 401(k) plan automatically qualify for ERISA 404(c)?
No. A participant-directed 401(k) plan must satisfy the applicable requirements under the 404(c) regulation. The existence of participant-directed investments alone does not automatically establish 404(c) protection.
Does ERISA 404(c) eliminate fiduciary liability?
No. The protection is limited. Plan fiduciaries generally remain responsible for fiduciary decisions such as the prudent selection and monitoring of the investment alternatives offered by the plan.
Does a 401(k) plan have to provide investment education to qualify for 404(c)?
The 404(c) regulation requires participants to be provided, or have the opportunity to obtain, sufficient information to make informed investment decisions. The Department of Labor also provides guidance concerning investment education and the distinction between education and investment advice.
How often should a plan review its 404(c) process?
There is no single annual “404(c) review date.” However, incorporating 404(c) requirements into the plan’s ongoing fiduciary governance and annual review process can help identify gaps in participant information, investment procedures, investment options, and documentation before they become larger problems.
Why should 404(c) responsibilities be documented?
Because documentation creates a record of what the plan fiduciaries and service providers actually did. It can clarify responsibilities, identify gaps, demonstrate follow-through, and help the committee understand how the plan was governed throughout the year.
Ready to Strengthen Your Fiduciary Process?
You don’t have to manage every fiduciary responsibility on your own. Fiduciary Wise helps plan sponsors bring structure, clarity, and ongoing oversight to their ERISA fiduciary responsibilities.